1 / 5
Does the 4% retirement rule actually work for Canadians, or is it built for Americans?
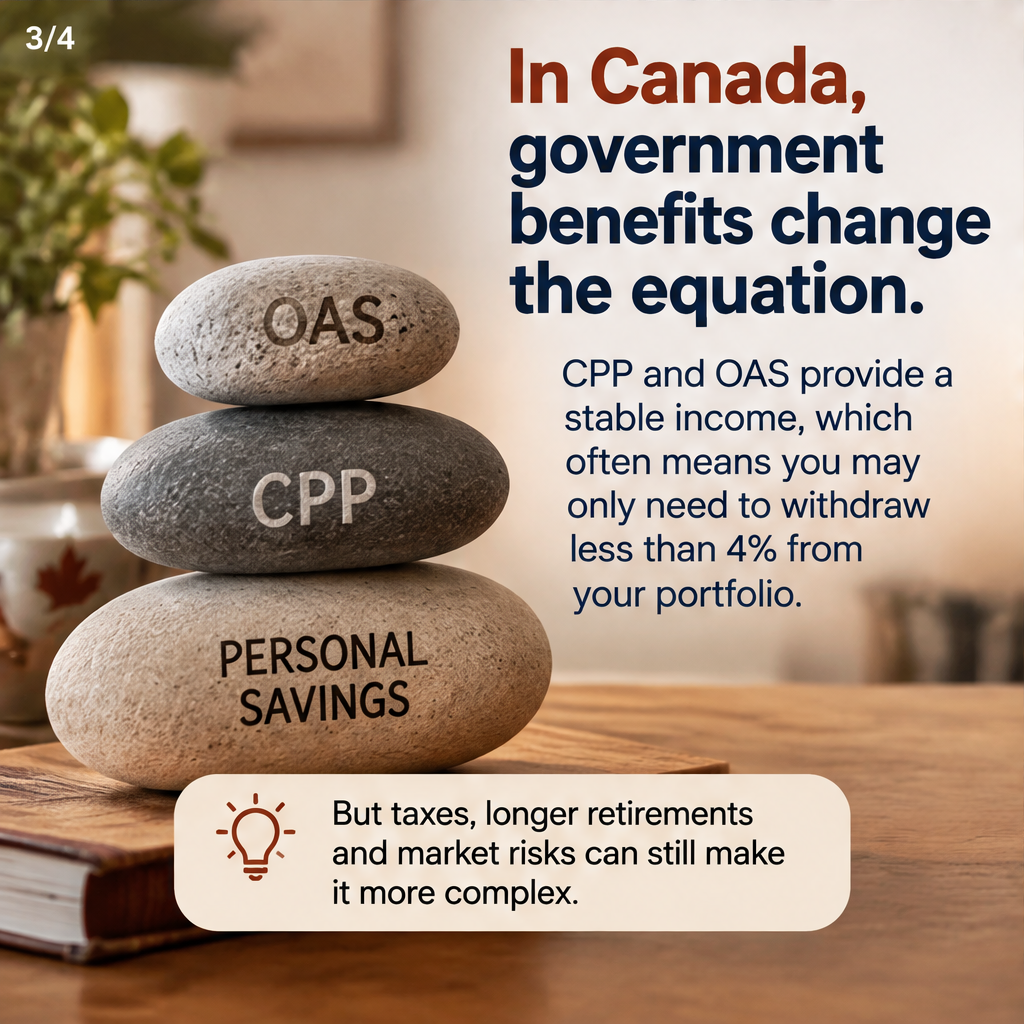
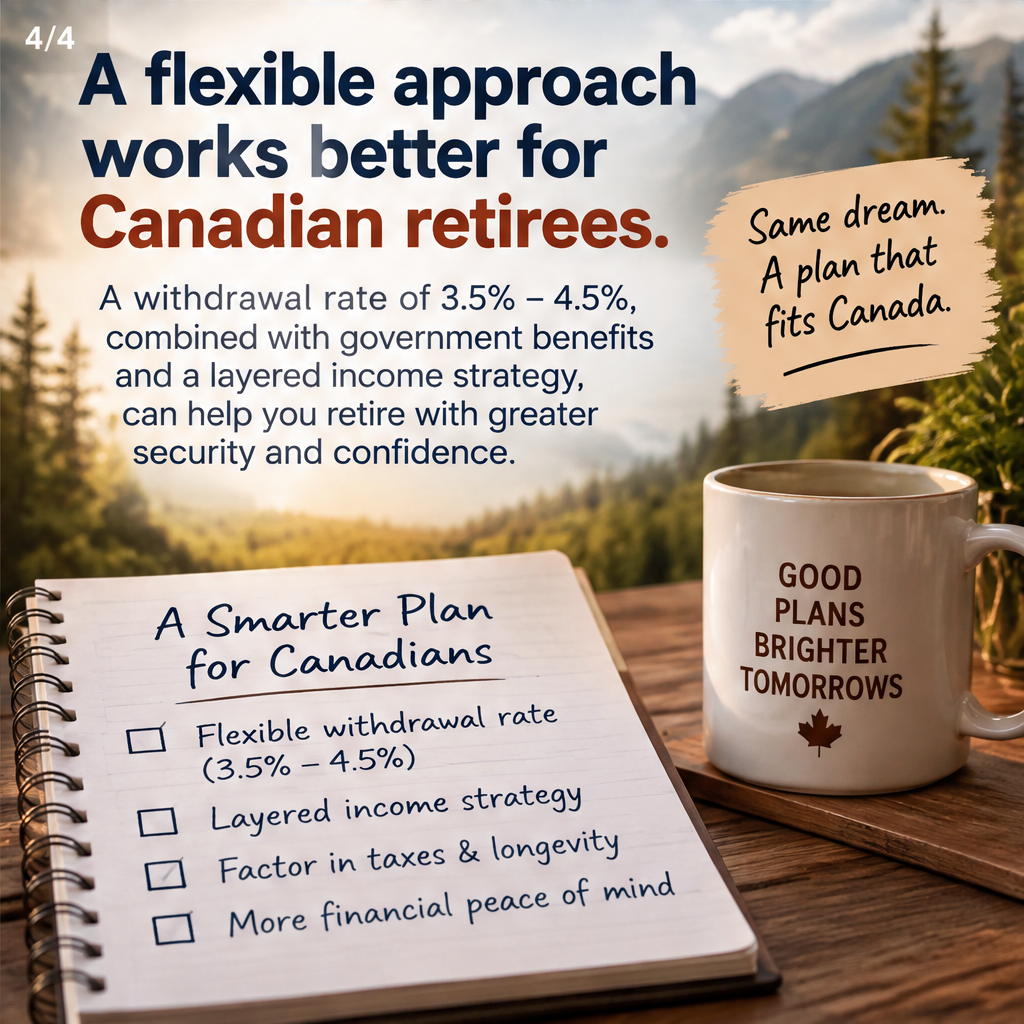
The 4% withdrawal rule suggests retirees withdraw 4% of their portfolio in the first year, adjusting for inflation annually, aiming to sustain a 30-year retirement. In Canada, government benefits like CPP and OAS reduce the needed withdrawal rate, often below 4%. Taxes, longer retirements, and market risks complicate its application. A flexible withdrawal rate of 3.5%-4.5% and layered income strategies better suit Canadian retirees.