Pre-Sale Condo? 4 Mortgage Checks Before You Sign
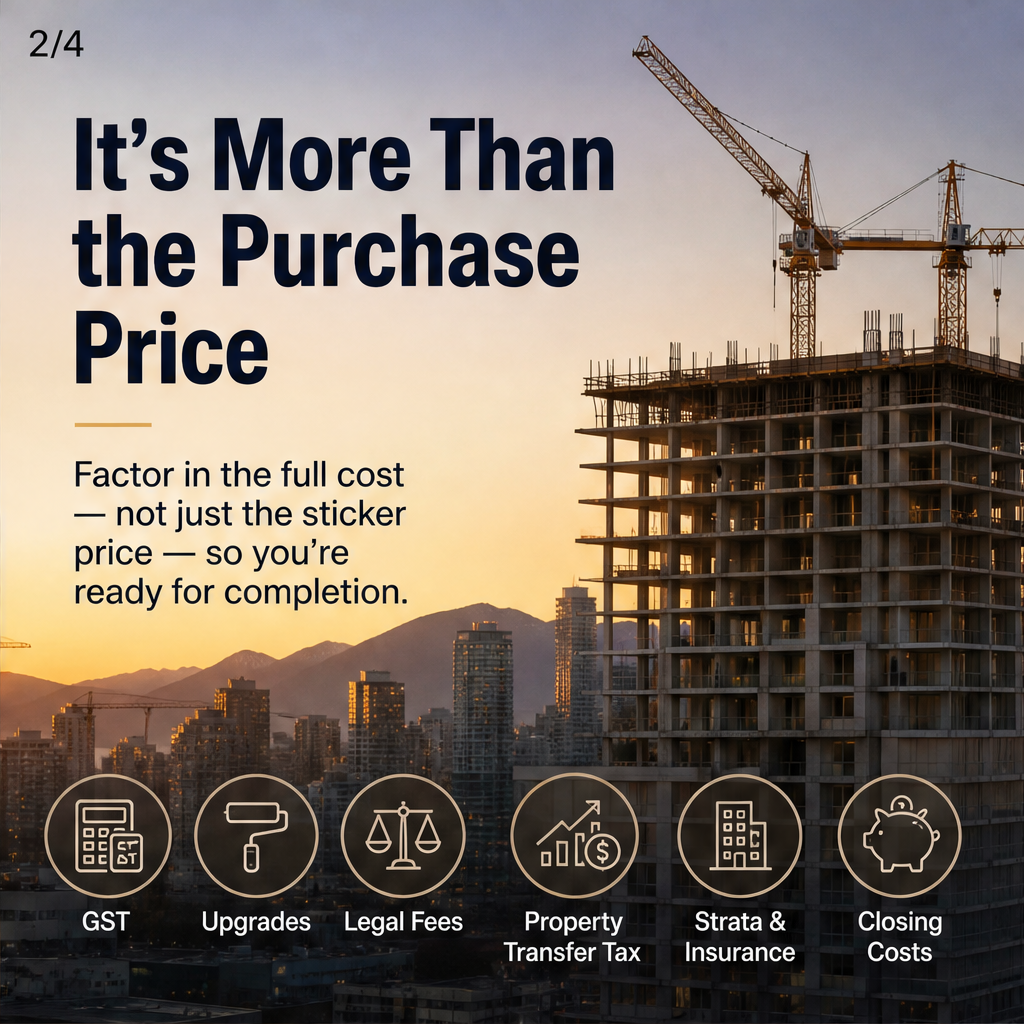
A pre-sale purchase can feel exciting, but the mortgage decision extends far beyond today’s purchase price. Before signing, calculate the complete cost, including GST, upgrades, legal fees, property transfer tax where applicable, strata fees, insurance, and other closing expenses. Build a realistic budget that leaves room for unexpected increases. Timing is another key consideration. Your mortgage approval may be based on current income, debts, lending rules, and interest rates, while completion could be several years away. Ask your mortgage broker how changing rates, employment, credit, or debt levels could affect qualification when the home is ready. Also review the deposit schedule and lender requirements carefully. Confirm whether your financing strategy works for each deposit milestone, understand rate-hold options, and ask about assignment restrictions or changes to the development. A pre-sale contract may have important deadlines and conditions that are difficult to change later. Before you commit, have a mortgage broker, lawyer, and other qualified professionals review the details with you. A proactive conversation today can help you avoid surprises and move toward completion with greater confidence. Reach out for a pre-sale mortgage planning review tailored to your Vancouver purchase.